
An umbrella policy adds limits above a staffing firm’s primary liability policies, but a higher limit on the declarations page doesn’t tell you whether a particular claim is covered. Staffing umbrella liability insurance pays above the underlying policies scheduled on it, subject to its own terms and conditions. When a claim looks likely to exceed a primary limit, agents need to answer two separate questions: How much insurance sits above the primary policy, and does the umbrella cover this type of claim?
What Happens When a Claim Exceeds Primary Limits?
Once a covered claim uses up the applicable underlying limit, the umbrella may pay the rest, up to its own limit. WWSPI’s umbrella can sit over professional liability, general liability, commercial auto liability, employee benefits liability, and employers liability.
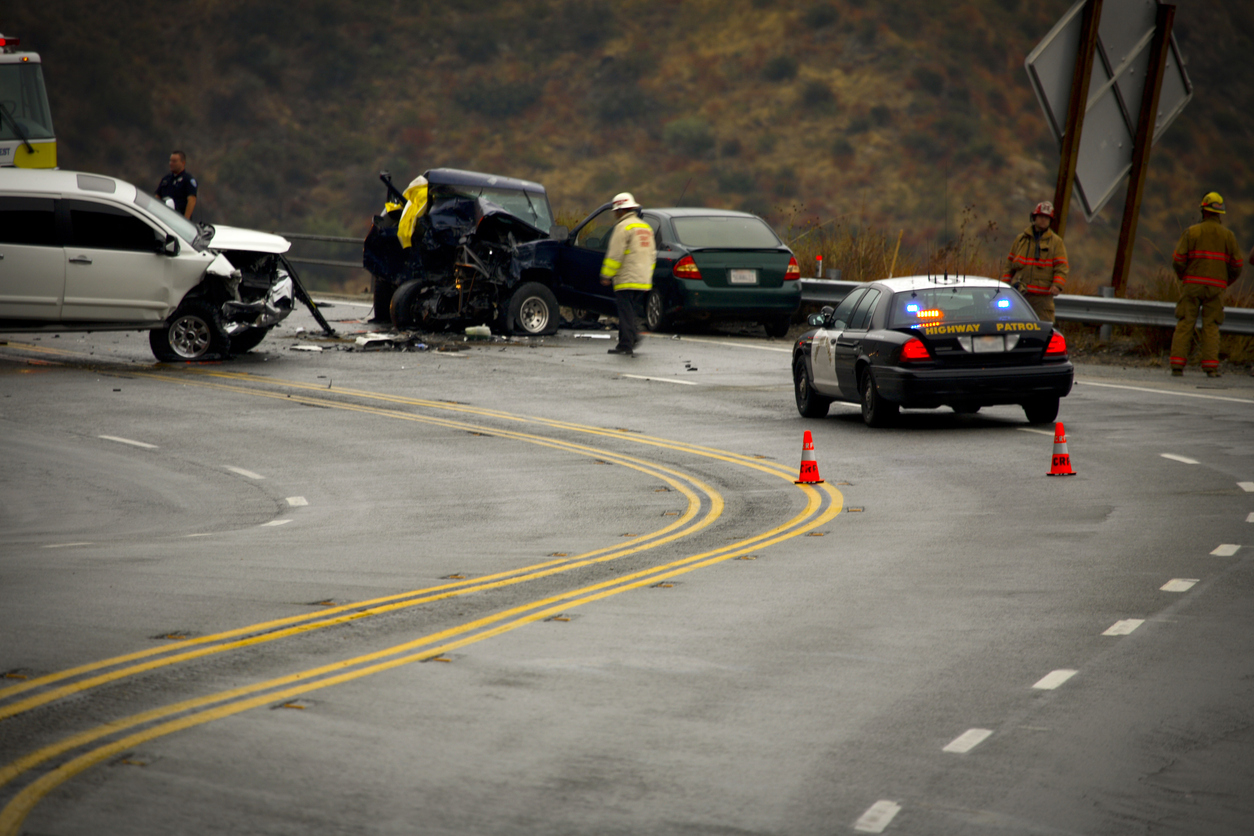
Auto claims show why the limit alone doesn’t answer the coverage question. A staffing firm with employees behind the wheel can face large injury claims. The National Highway Traffic Safety Administration estimates the lifetime economic cost of a single crash fatality at $1.6 million and puts the average for a critically injured survivor at $979,000, before counting lost quality of life. The same report notes that individual cases can run three times the average or more.
A crash like that can go past a $1 million auto limit. Whether the umbrella then pays depends on whether the auto policy is on the umbrella’s schedule, whether the firm kept the underlying limit the umbrella requires, and whether the umbrella’s terms cover the claim. Going over the primary limit doesn’t trigger umbrella coverage on its own.
Where Could the Policies Differ?
Three checks show whether the umbrella and the underlying policies line up:
- Scheduled policies: Confirm the policy that would respond first appears on the umbrella’s schedule of underlying insurance. A policy the firm added during the term, such as owned auto coverage for newly purchased vehicles, may need to be reported and added.
- Limits and terms: Compare each underlying limit with the limit the umbrella requires. Umbrella policies hold the insured responsible for keeping the scheduled underlying policies in force without changes during the umbrella term, so a lowered limit or a lapsed policy can create a problem the firm won’t see until a claim comes in.
- The exposure: Read how the umbrella handles the type of claim in question, including its own definitions and exclusions.
A gap in an underlying policy doesn’t mean the umbrella fills it. Some umbrella provisions follow the form of the underlying policy, so an exclusion there carries up to the umbrella. Others provide coverage for certain exposures the underlying policies leave out. WWSPI’s umbrella includes both: It follows form over professional liability, general liability, employee benefits liability, and employers liability, and it covers some exposures the underlying policies don’t. Commercial auto isn’t on the follow-form list, so read the umbrella’s auto provisions rather than assuming they mirror the auto policy.
The umbrella’s own wording decides how it responds. When a question comes down to a specific account or claim, ask the underwriter before telling the client what to expect.
Review the Full Policy Structure
The umbrella limit tells you how much insurance sits above the primary policies. The schedule, the underlying limits, and the umbrella’s wording tell you whether that insurance applies to a given claim. Review them together at quote and at each renewal, and again when a client signs a contract with higher limit requirements, adds vehicles, or starts placing workers in new types of jobs. Once the structure checks out, you can move on to how much umbrella coverage the firm needs.
Call us to review the umbrella structure on a staffing account before its next renewal.
About World Wide Specialty Programs
For the last 50 years, World Wide Specialty Programs has dedicated itself to providing the optimal products and solutions for the staffing industry. As the only insurance firm to be an ASA commercial liability partner, we are committed to that partnership and are committed to using our knowledge of the industry to provide staffing firms with the best possible coverage. For more information about Staffing Professional Liability Insurance or any other coverage we have available to protect your staffing business, give us a call at (877) 256-0468 to speak with one of our representatives.