
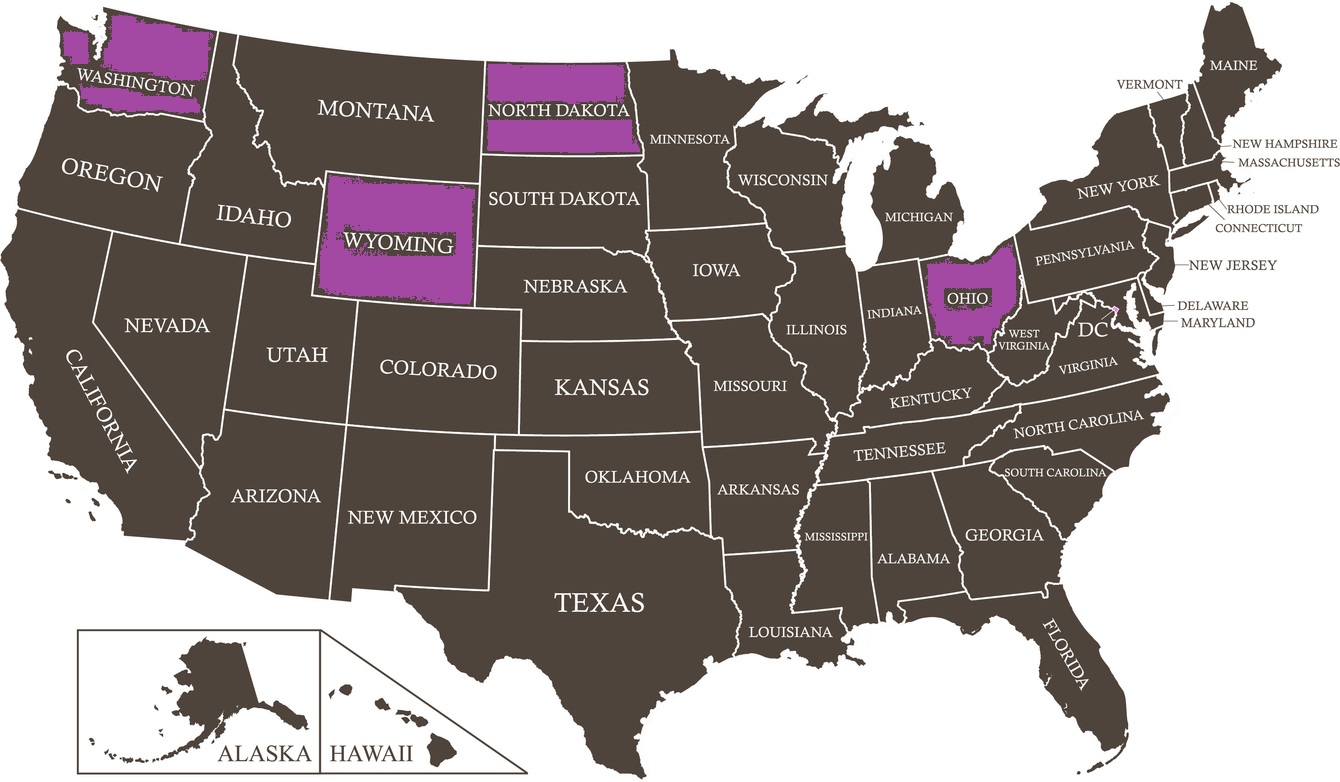
What is stop gap insurance, and does a particular staffing account need it? Stop gap supplies employers liability protection in the monopolistic workers’ compensation states of North Dakota, Ohio, Washington, and Wyoming, where state fund policies leave it out. Whether a staffing firm needs the coverage depends on where its employees work, how its workers’ compensation is arranged, and what liability coverage it already carries. Agents can sort through all three before a submission goes out, and the answers show whether an account is ready for an underwriter’s review.
What Is Stop Gap Insurance for Staffing Firms?
Stop gap insurance provides employers liability coverage in North Dakota, Ohio, Washington, and Wyoming. Employers in those states get workers’ compensation through the state, and the state policy pays statutory benefits only. Outside those four states, a standard workers’ compensation policy includes employers liability as Part Two, so stop gap fills in what the state policy leaves out.
Employers liability responds when an employee alleges the employer is legally liable for a work-related injury or illness beyond what the workers’ compensation law requires, such as a claim that the employer failed to keep the workplace free of known hazards, as federal law requires. For a staffing firm, that allegation can involve a client’s job site rather than the firm’s own office, since its workers report to client facilities every day.
Stop gap uses the same three limits found in standard employers liability coverage:
- Each accident: Caps what the policy pays for injuries from a single accident
- Disease, each employee: Caps what it pays for any one employee’s work-related illness
- Disease, aggregate: Caps the total it pays for all illness claims during the policy period
If a client contract calls for employers liability limits on an account with workers in one of these four states, stop gap is where those limits come from.
What Should Agents Confirm Before Submission?
If a stop gap submission leaves out details about placements, general liability, or existing coverage, the underwriter will have to ask for them before reviewing the account. Checking those details first saves time and tells the agent early whether the account fits the program. Three checkpoints cover what to confirm.
Checkpoint 1: Where Are Employees Being Placed?
Start with placement and payroll records rather than the headquarters address. A staffing firm based in Indiana may place light-industrial workers across the Ohio line, and a branch in Oregon may send healthcare contractors to facilities in Washington. Review assignments outside the home state, internal employees who work remotely, and any branch offices in North Dakota, Ohio, Washington, or Wyoming. Activity in one of those states gives you a reason to keep digging. It doesn’t establish that the account qualifies.
Checkpoint 2: Is General Liability in Place?
WWSPI writes stop gap together with general liability coverage, so start by confirming the firm carries a general liability policy and noting where it’s written. If the policy is with another carrier, renews on a different schedule, or is set up in a way you’re unsure about, check with the underwriter on how it fits before you build the submission.
Checkpoint 3: Is There an Employers Liability Gap?
For each monopolistic state where the firm has employees, work through three questions in order. Are employees working there now? Does their workers’ compensation run through the state system? Does any existing policy provide employers liability for them? If the answer to the last question is no, the firm has a potential gap to raise with the underwriter.
Resolve Coverage Questions Before Submission
Three checks frame a stop gap question for a staffing account: where employees work, whether general liability is in place, and whether employers liability is missing in a monopolistic state. A yes on all three makes the account worth a conversation with the underwriter about the account’s eligibility for stop gap coverage. Bring open questions about eligibility or policy structure to the underwriter before the submission goes out.
Contact us to discuss stop gap for a staffing account with employees in North Dakota, Ohio, Washington, or Wyoming.
About World Wide Specialty Programs
For the last 50 years, World Wide Specialty Programs has dedicated itself to providing the optimal products and solutions for the staffing industry. As the only insurance firm to be an ASA commercial liability partner, we are committed to that partnership and are committed to using our knowledge of the industry to provide staffing firms with the best possible coverage. For more information about Staffing Professional Liability Insurance or any other coverage we have available to protect your staffing business, give us a call at (877) 256-0468 to speak with one of our representatives.